
A crypto validators’ dashboard may show rewards arriving regularly. That does not mean the operation is profitable. The operator has to keep a node running, maintain its software and protect the keys that authorise its actions.
In return, income can come from protocol rewards, transaction fees and, in some circumstances, additional revenue linked to transaction ordering.
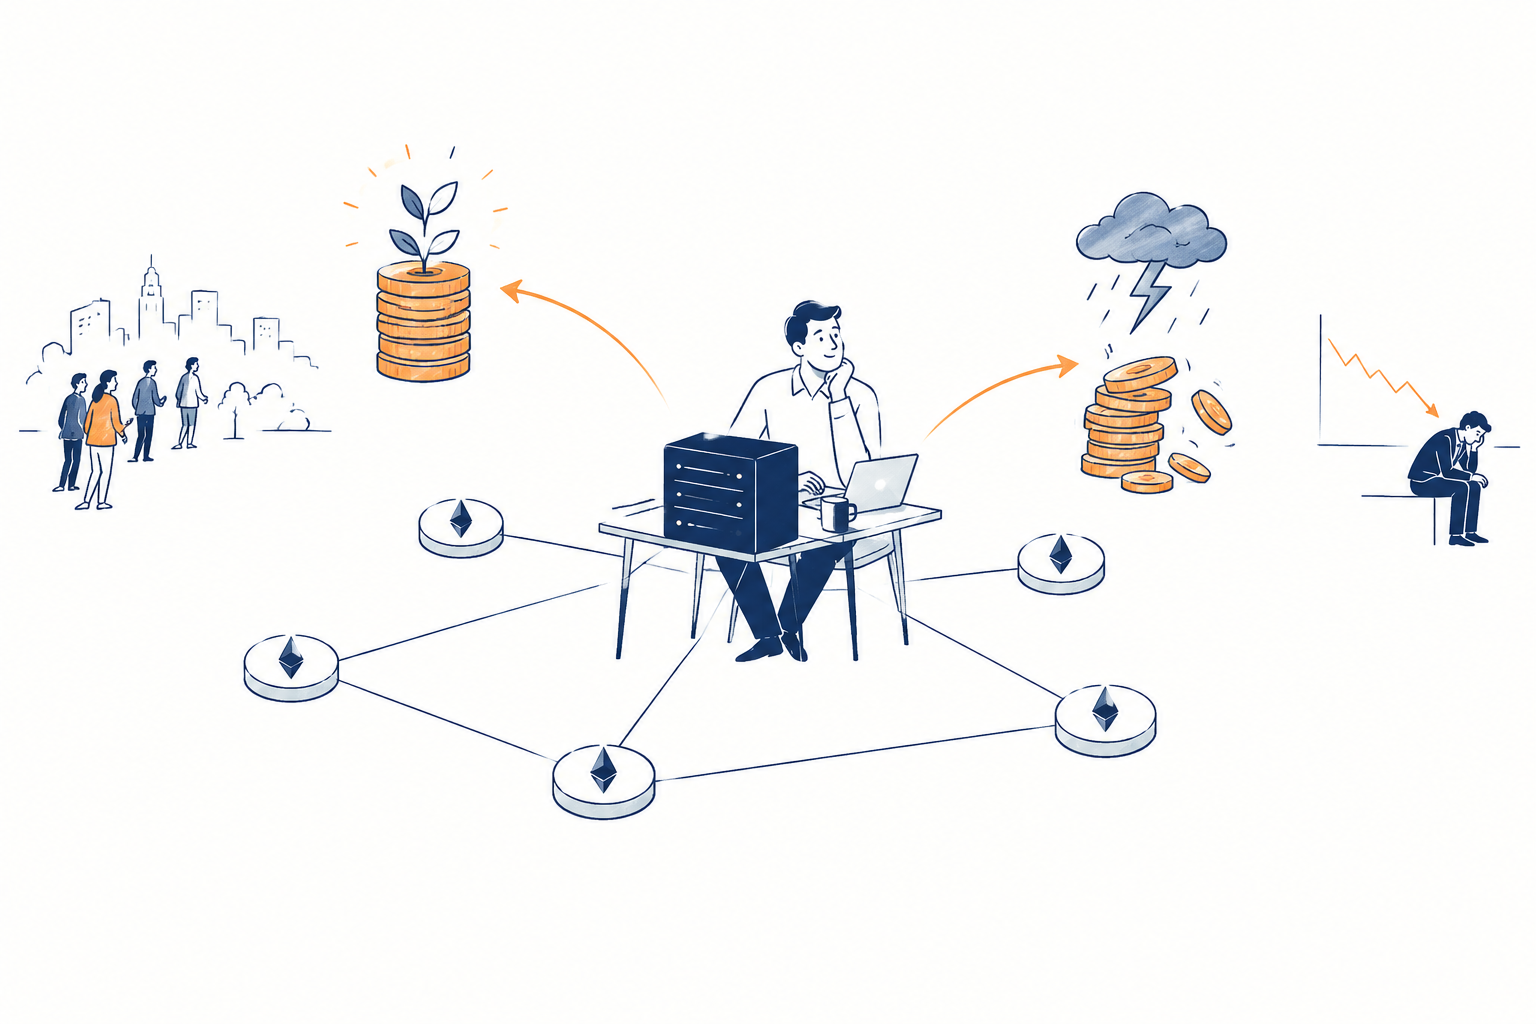
The real question is what remains after the costs and risks of earning those rewards. A validator can accumulate more cryptocurrency while its income loses value in pounds, or run reliably while spending more on infrastructure than it earns.
How do crypto validators make money?
In a proof-of-stake (PoS) blockchain, crypto validators help the network agree on which transactions are valid and which blocks should be added to the chain. They run validator software and carry out duties defined by the protocol.
On Ethereum, for example, validators attest to blocks and may be selected to propose one. The protocol rewards eligible participation, with the amount depending on factors such as the validator’s effective stake, performance and network rules.
Some rewards are funded by the issuance of new tokens. That increases the number of tokens a validator holds, but it does not guarantee that the rewards will be worth more in pounds. If the token’s market price falls, the sterling value of the income can fall even when the validator receives the expected amount of cryptocurrency.
It is also important to distinguish operating a crypto validator from delegating tokens to one. A delegator assigns stake to an operator and typically receives a share of the rewards, after any commission.
The operator is responsible for keeping the service running and may earn a commission on delegated stake, alongside rewards generated by any tokens it has staked itself.
The exact arrangement varies by blockchain and staking model. The advertised return for a delegator, therefore, is not necessarily a measure of the operator’s profitability.
Transaction fees can add another revenue stream, although not every validator receives them in the same way. On Ethereum, the base fee is burned, while the priority fee can go to the validator proposing the block. Since crypto validators are not all selected to propose blocks equally often over short periods, this income can be uneven.
Other networks follow different fee rules, so an Ethereum example should not be treated as a template for every chain.
There is also maximal extractable value, or MEV. It describes the extra value that can be captured by choosing which transactions to include in a block and how to order them. Searchers identify opportunities, and block builders may assemble transactions into a proposed block.
A validator can receive part of this value through the fees or bids associated with block inclusion, depending on how the network’s system is organised.
MEV is competitive and variable, however. It is not a guaranteed payment that every validator should expect in every period. Treating it as dependable income can make an operation look more profitable on paper than it proves to be in practice.
The costs that staking rewards do not show
Rewards are only the revenue side of the calculation, crypto validators needs reliable hardware or hosted infrastructure, a stable internet connection, monitoring, software updates, backups and secure key management. Depending on the setup, the operator may also pay for electricity, storage, specialist tools or external support.
The amount varies with the blockchain and the level of resilience the operator wants. There is no single operating cost that applies to every validator.
Time is another expense, even when the software largely runs automatically. Someone needs to notice outages, deal with client updates and respond when the network or infrastructure behaves unexpectedly. A low-cost setup that regularly misses duties may turn out to be more expensive than a better-maintained one.
The stake itself also matters. Some networks restrict when committed tokens can be withdrawn or require an exit process before funds become available. The tokens still belong to the staker, but the capital may be less liquid than assets held in an ordinary wallet.
It also has an opportunity cost: the same funds could have been used elsewhere, with different risks and possible returns. This does not make the staked capital an operating expense in the same sense as a server bill, but it matters when comparing the overall return with alternative uses of the funds.
For an operator who measures the business in pounds sterling, currency exposure complicates the picture. A validator might earn the amount of ETH or another token it expected, yet have less money available to cover a server bill if that token has fallen against sterling.
A price increase can improve the result without making the underlying operation any more reliable or efficient.
This is why published staking yields can be misleading when taken alone. They usually describe rewards relative to a stake, not the operator’s full costs, time commitment, asset-price risk or income from delegated stake after commissions and expenses.
Downtime and slashing can change the calculation
A validator’s performance affects its income. When it is offline or fails to complete an assigned duty, it may miss a reward; some networks also impose penalties for particular failures or prolonged inactivity.
Problems can stem from internet interruptions, hardware faults, poorly handled upgrades or mistakes in the software configuration.
Slashing is more serious, but it is not simply another word for downtime. It is a protocol penalty for specific rule-breaking behaviour, such as signing conflicting block proposals or attestations. On Ethereum, these offences can trigger a loss of staked ETH and removal from the active validator set.
An ordinary outage does not, by itself, amount to slashing. The rules differ between networks, so an operator needs to understand the relevant protocol rather than assume that every chain treats failures alike.
Key management is particularly important because an operator can create risk through its own setup. For example, running duplicate signing processes with the same validator keys can produce conflicting signatures. The technical safeguards used to prevent such mistakes are part of the real cost of operating securely, not an optional extra.
Slashing is not an everyday operating expense to be casually averaged into a forecast. It is a downside risk that can be infrequent but material. A realistic assessment should therefore consider both routine performance — how consistently the validator earns rewards, and the safeguards in place to prevent a costly failure.
A validator’s return is more than its reward rate
A useful starting point is to calculate the income that actually belongs to the operator: rewards on its own stake, commissions retained from delegated stake, transaction-related revenue and any MEV-related income.
From that, subtract infrastructure and service costs, as well as any penalties. Rewards passed on to delegators should not be counted as the operator’s own income.
Even that calculation is incomplete if it ignores the value of the capital committed and changes in the token’s price. It is helpful to track results in both tokens and pounds, over a meaningful period rather than judging the operation by a single unusually profitable block or month.
Scale can improve the economics. An operator managing many crypto validators may spread monitoring, maintenance and infrastructure costs across a larger operation. It may also have more resources to invest in uptime and security.
Smaller operators, by contrast, may find it harder to match those efficiencies.
That creates a tension for proof-of-stake networks. Professional operators can make validation more dependable, but if operating at scale becomes a decisive advantage, stake and validation services may concentrate among fewer participants.
The network may benefit from better-run infrastructure while becoming less distributed.
So, how do crypto validators make money? They earn protocol rewards and, in some networks and circumstances, transaction fees or MEV-related income. Whether that income amounts to a sustainable business depends on what the operator retains, what it spends, how it manages penalties and what those tokens are worth when the bills come due.
The reward is visible on-chain; the true return has to be worked out.