
The first generation of stablecoin adoption was easy to see. A user bought USDT or USDC, moved it to a wallet and sent digital dollars across a blockchain. The stablecoin itself was the product.
The next phase may look very different.
A company can use stablecoins to settle a cross-border payment without exposing them to the customer. A fintech can offer a dollar-denominated account while handling tokens and blockchain networks behind the interface.
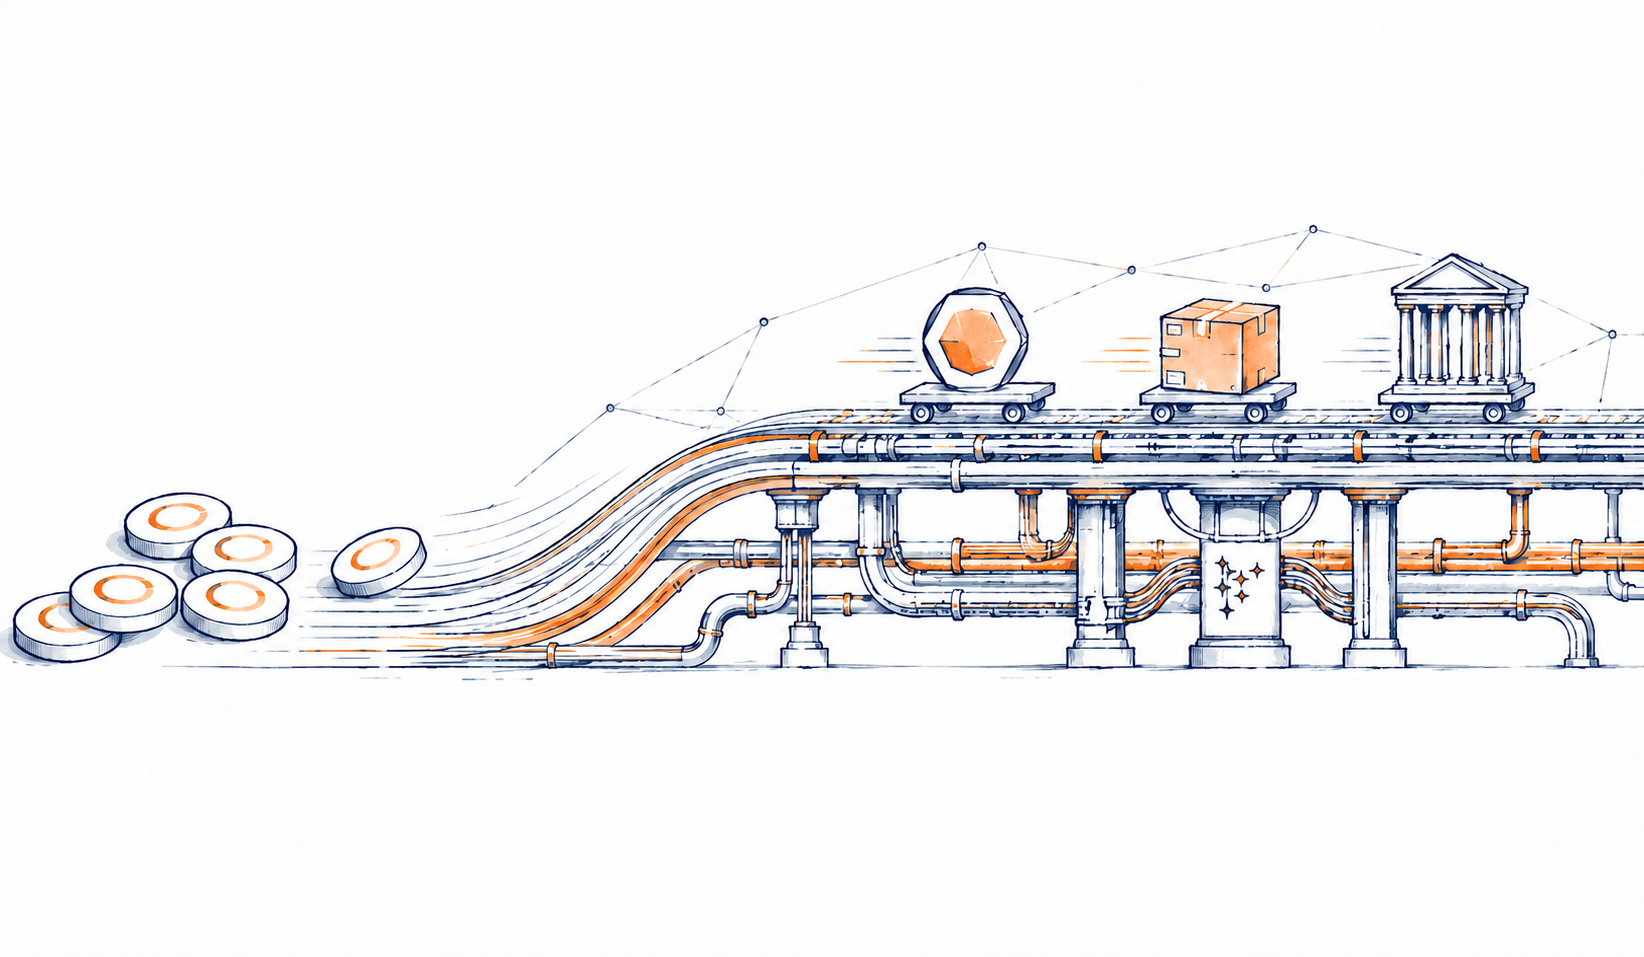
Financial institutions can also move liquidity between markets while their clients continue interacting with familiar currencies and products. In that model, stablecoins are no longer primarily competing for a place in someone’s wallet. They are competing for a place inside the machinery that moves money.
That transition helps explain why Fasset has just raised $68 million in a Series C led by Japan’s SBI Group at a $1 billion valuation. The company had raised another $51 million only three months earlier, bringing its 2026 funding to $119 million.
Fasset connects banks, payment companies, telecom operators and liquidity providers across more than 100 international corridors. Its expansion plans include stablecoin settlement, banking corridors and tokenized assets.
Investors are therefore not simply funding another venue for people to hold digital dollars. They are funding infrastructure designed to expand what those dollars can do.
The Hard Part Begins After the Stablecoin Moves
Blockchains solved an important part of moving money. A dollar represented by a token can travel continuously between addresses without requiring the same chain of correspondent banks and messaging systems traditionally used to move value across borders.
But completing a blockchain transaction and completing a financial transaction are not always the same thing.
A business receiving stablecoins may need Brazilian reais to pay employees. A supplier may want euros deposited into a bank account. Financial institutions still need to identify customers, comply with sanctions and anti-money-laundering rules, manage foreign exchange and connect digital assets to local payment networks.
The token can move value between two points, but an entire financial system still exists around those points. That is where companies building stablecoin infrastructure are positioning themselves: connecting blockchain settlement with liquidity providers, banks, payment systems and fiat currencies.
The objective is not necessarily to convince every participant in a transaction to adopt crypto. It is to make stablecoins useful even when they do not.
That opens a potentially much larger market than crypto-native payments because the end user no longer needs to become a blockchain user before the infrastructure can benefit from blockchain settlement.
Stablecoins Do Not Need to Defeat Banks
The early stablecoin narrative often presented banks as the incumbent that blockchain money would eventually displace. The structure now emerging is less binary.
Banks perform many functions that issuing a digital dollar does not reproduce. They maintain customer relationships, provide access to domestic payment networks, perform compliance, manage accounts and connect businesses to local financial systems.
Stablecoins can leave many of those functions intact while changing what happens between financial institutions.
Cross-border payments illustrate the distinction. Traditional international transfers can require correspondent banking relationships, prefunded accounts and multiple intermediaries. Stablecoins offer an alternative settlement asset that can move continuously across a shared digital network.
The endpoints can still be conventional financial institutions.
The Financial Stability Board has pointed toward precisely this kind of hybrid architecture, in which stablecoins interact with commercial bank money, foreign exchange and existing settlement systems rather than developing as a completely separate global payments network.
Stablecoins could therefore prove more complementary to banks than their original narrative suggested. A bank does not have to disappear for its underlying payment rails to change, and a fintech does not necessarily need to become a bank before it can build services on top of those new rails.
Infrastructure Wins When Users Stop Thinking About It
The most consequential stage of stablecoin adoption may also be the least visible.
Today, stablecoin growth is often measured through supply, transaction volumes, active addresses or the number of people holding USDT and USDC. Those metrics capture direct adoption, but they become less complete if stablecoins increasingly operate behind financial products.
A customer sending money abroad may never know that a stablecoin briefly carried the value between two institutions. A business may see dollars enter one account and local currency arrive in another without choosing a blockchain.
A financial platform may route liquidity on-chain while presenting users with an interface that looks no different from conventional banking software. At that point, asking how many customers consciously use stablecoins becomes less important than asking how much financial activity relies on them.
The transition is still early. Stablecoins account for only a small portion of global cross-border financial flows, and many institutional use cases remain experimental.
Fasset reaching a $1 billion valuation does not prove that stablecoin rails will replace today’s payment infrastructure. It does show where capital is beginning to see value.
The first stablecoin companies had to convince people that dollars could exist on a blockchain. The companies building the next layer may have a different task: making the blockchain irrelevant to the user.
Stablecoins began by putting money on-chain. Their bigger opportunity may be becoming the infrastructure that moves money while almost nobody notices they are there.