
Wall Street processes enormous trading volumes without moving the gross value of every transaction between buyers and sellers.
That is not an accident.
Clearing infrastructure allows obligations to offset one another before final settlement. If one institution owes another $100 million while it is due to receive $90 million from the same system, the market does not necessarily need to move $190 million between them.
Netting can dramatically reduce what ultimately has to be delivered.
The Depository Trust & Clearing Corporation says multilateral netting at its National Securities Clearing Corporation reduces payment obligations in U.S. equities by an average of 98%. Its infrastructure processed $608 trillion in equity transactions in 2025.
Solana is now bringing a very different settlement architecture to financial institutions.
The Solana Foundation has launched Solana DvP, an open-source delivery-versus-payment program designed to exchange an asset and its payment atomically on-chain. J.P. Morgan provided input on institutional settlement practices and requirements during its development.
The attraction is obvious: settlement can happen in seconds.
The more interesting question is what has to be available before those seconds begin.
Wall Street Uses Time to Reduce What Has to Move
In traditional securities markets, execution and settlement are separate events.
A trade can be agreed now while the final exchange of securities and cash happens later. In U.S. equities, the standard settlement cycle moved from T+2 to T+1 in 2024.
That interval creates exposure. A counterparty could fail before settlement is completed, which is one reason clearing houses, margin requirements and other risk-management mechanisms exist.
But the interval also gives market infrastructure an opportunity to aggregate obligations.
Rather than treating every purchase and sale as an isolated movement of securities and cash, clearing systems can calculate what participants ultimately owe one another.
The difference can be enormous.
DTCC’s 98% average reduction in payment obligations illustrates why clearing cannot be understood simply as technological friction between a trade and its settlement.
It is also a mechanism for using liquidity more efficiently.
Solana Removes a Different Risk
Solana DvP approaches the problem from another direction.
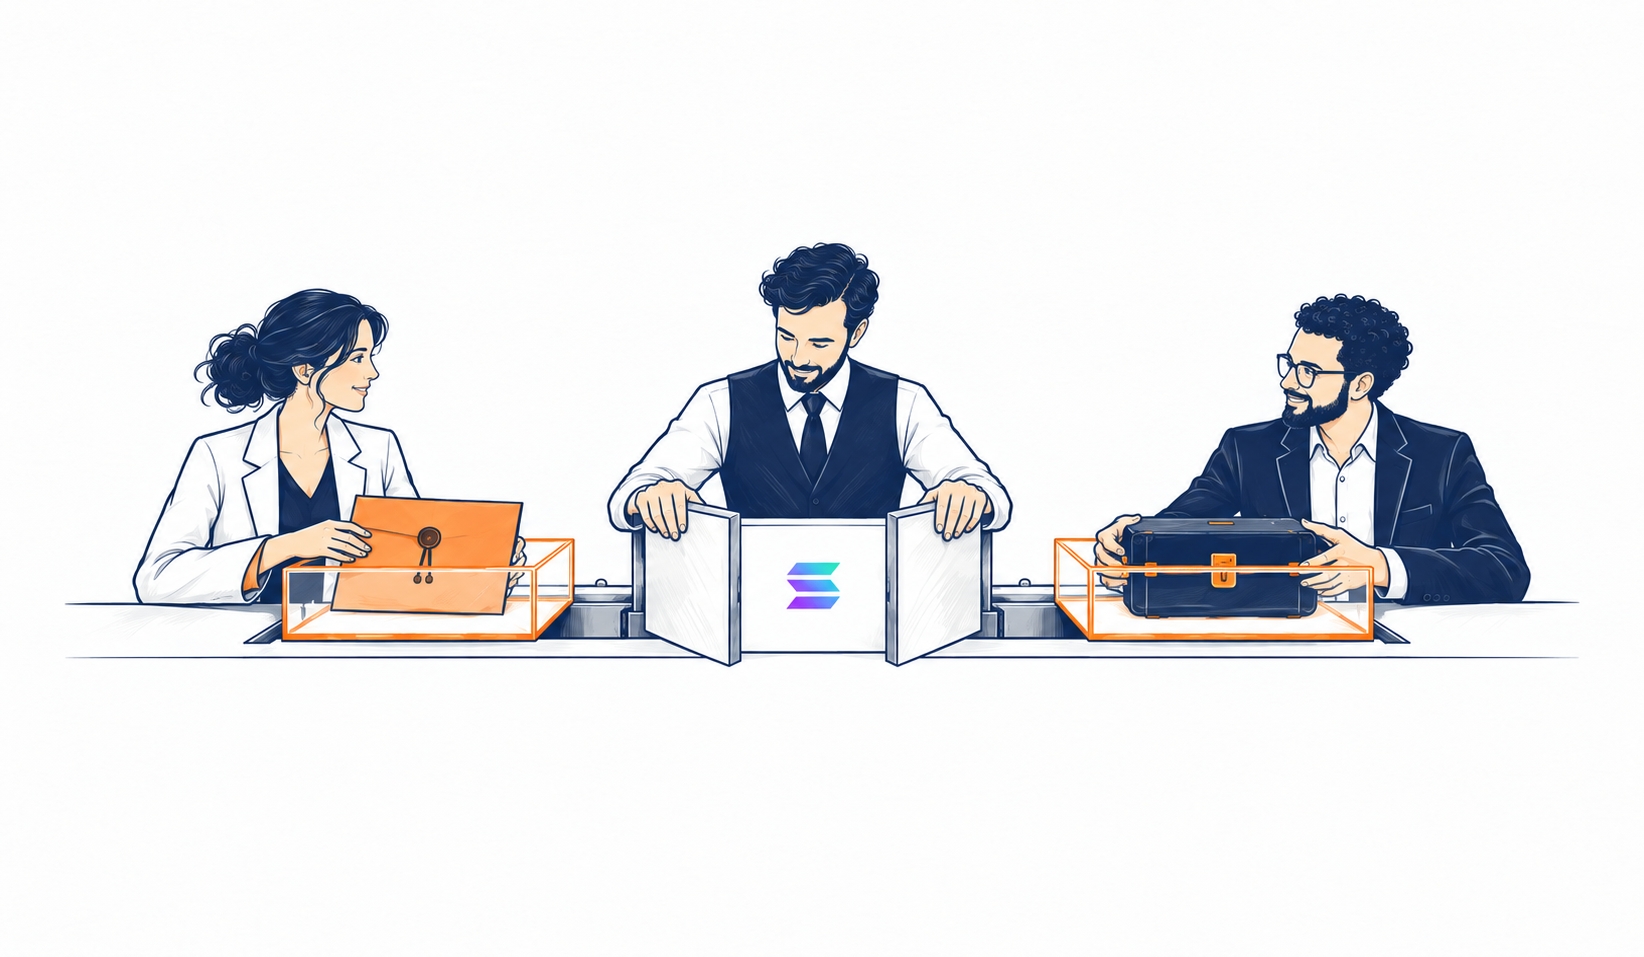
Each settlement record represents a bilateral trade. The seller deposits the asset into escrow, while the buyer provides the corresponding payment. Once both legs are sufficiently funded, a settlement authority can execute them atomically.
Either the asset and money move together or neither moves.
That addresses principal risk directly.
The seller does not have to deliver an asset and then wait to discover whether payment arrives. The buyer does not send money and depend on a separate process to receive the security.
Blockchain turns both legs into one settlement event.
But the program deliberately stops there.
Solana’s documentation says the DvP program does not perform trade matching, provide financing or conduct netting. It also does not support partial settlement. Those functions would have to exist elsewhere if a market requires them.
That distinction matters.
Atomic settlement can make an individual transaction safer without automatically making the entire market more capital-efficient.
Instant Settlement Changes the Liquidity Problem
Moving from next-day settlement toward near-instant settlement sounds like a straightforward technological upgrade.
Economically, it is more complicated.
A gross settlement model requires the resources needed for a transaction to be available when that transaction settles. A net settlement model can first offset multiple obligations and require participants to deliver only what remains.
The Bank for International Settlements has long distinguished between delivery-versus-payment models that settle securities and funds trade by trade and models that net one or both legs before final settlement.
Neither architecture eliminates trade-offs.
Waiting longer leaves transactions exposed for longer.
Settling faster can increase the amount of liquidity that participants need at a particular moment if obligations cannot first be offset.
This is why T+0 is not simply T+1 with a faster computer.
When U.S. markets shortened the cycle to T+1, DTCC reported that the NSCC clearing fund fell from $12.8 billion to $9.2 billion in the months following implementation, freeing approximately $3.6 billion. Faster settlement reduced the amount of risk that had to be collateralized.
But DTCC has also argued that moving all the way to same-day settlement could sacrifice some of the capital efficiencies created by netting if the surrounding market structure is not redesigned.
Speed can release capital in one part of the system while demanding more liquidity in another.
Blockchain Does Not Have to Choose Forever
None of this means an on-chain market cannot use netting.
Solana DvP is a settlement primitive, not a complete replacement for the clearing and post-trade infrastructure of a securities market.
That distinction may ultimately be its most important feature.
Markets could build credit, liquidity management, netting or other mechanisms around atomic settlement rather than requiring one smart contract to reproduce every function performed by existing market infrastructure.
The result would not necessarily look like either today’s Wall Street or today’s crypto markets.
It could combine the properties that blockchain handles particularly well — programmable assets, atomic exchange and continuous infrastructure — with financial mechanisms developed over decades to reduce the amount of capital required to support enormous trading volumes.
That is also why the comparison between seconds and T+1 can be misleading.
The two systems are not optimizing only for time.
Traditional clearing infrastructure has spent decades reducing how much money and how many securities must actually move after millions of trades have been matched.
Solana DvP attacks another variable: how long two counterparties must remain exposed before an asset and its payment can move together.
The next stage of market infrastructure may have to optimize both.
Making settlement faster is a technological problem. Making it faster without making capital less efficient is a market-design problem.